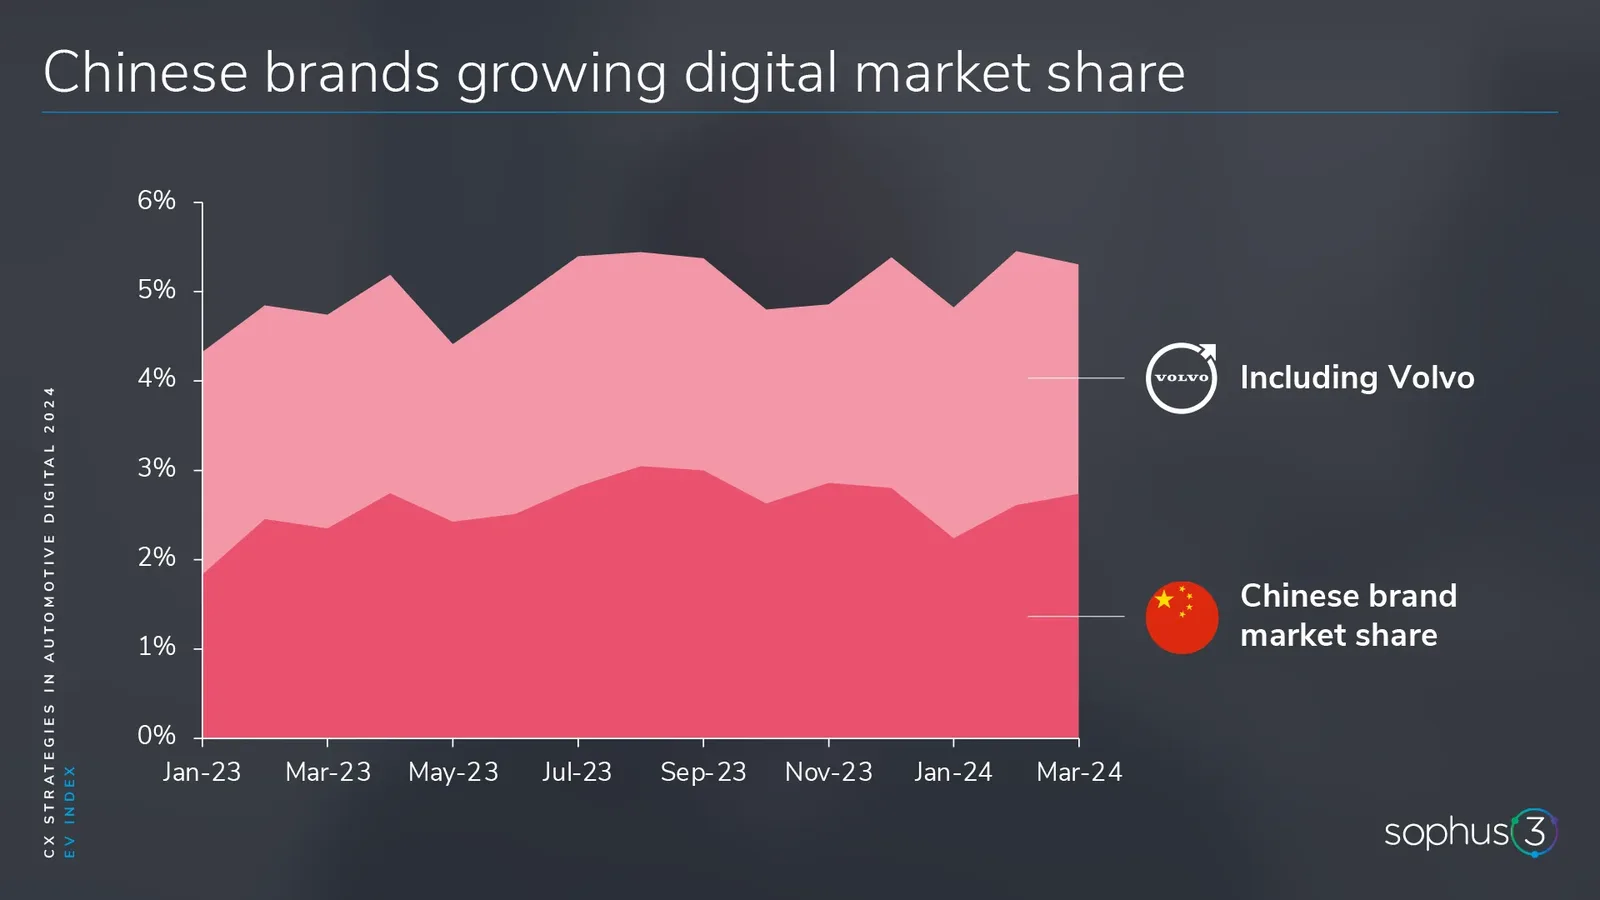
Chinese brands reached almost 3% of digital market share in 2024, with typical EVs 20% cheaper than European equivalents.
In this insight
Watch the videoDigital market share approaching 3%Failures, newcomers and a price advantageThe online landscape for Chinese brandsWatch the video
Sam Robson, Digital Analyst at Sophus3, discusses the mixed fortunes of Chinese car brands entering the European market and how their digital presence has grown rapidly in recent months. Watch the video on YouTube.
Digital market share approaching 3%
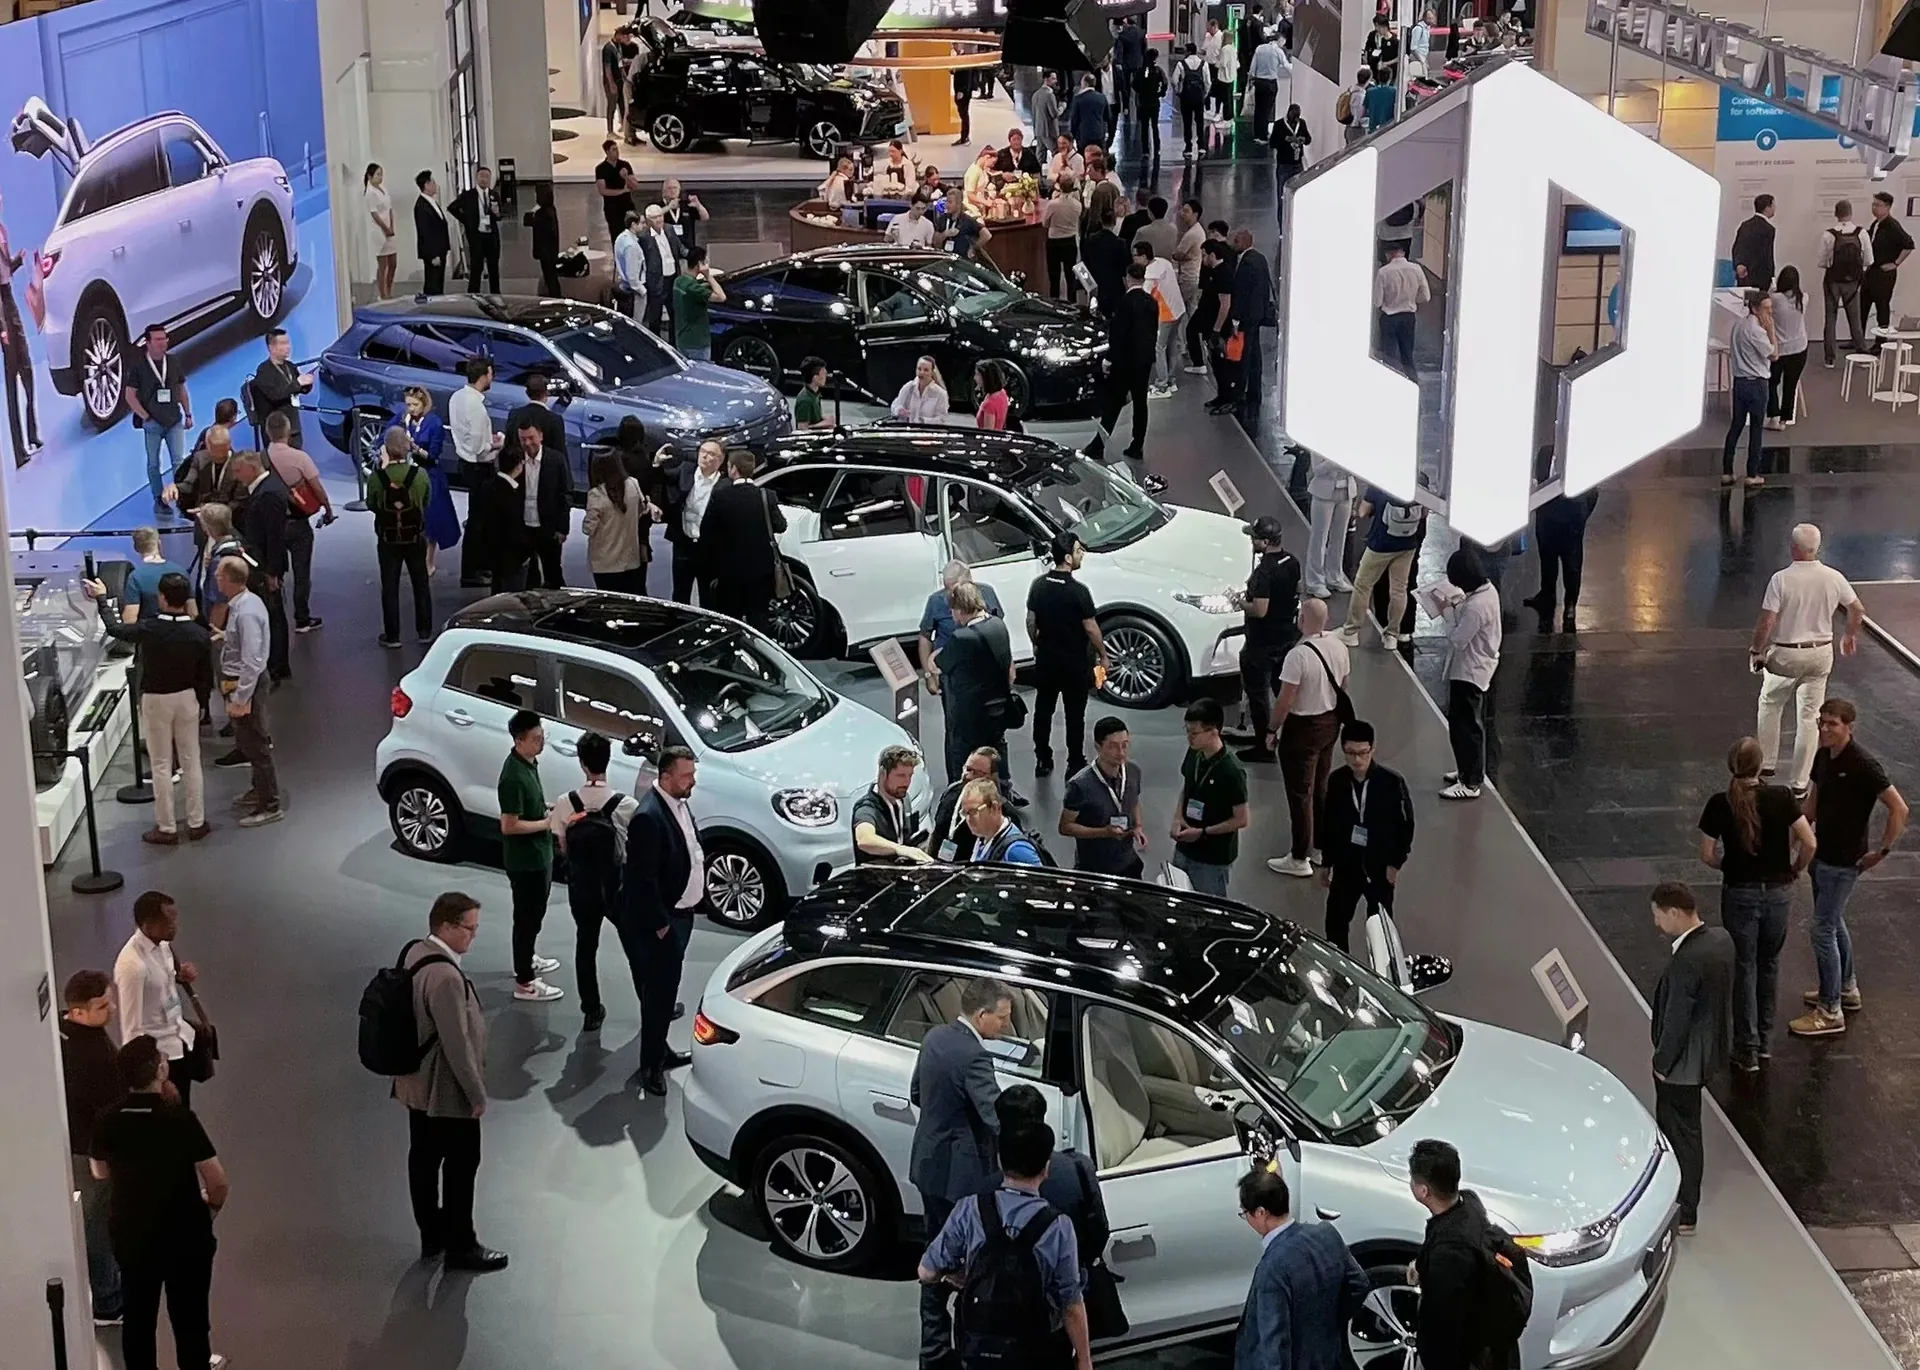
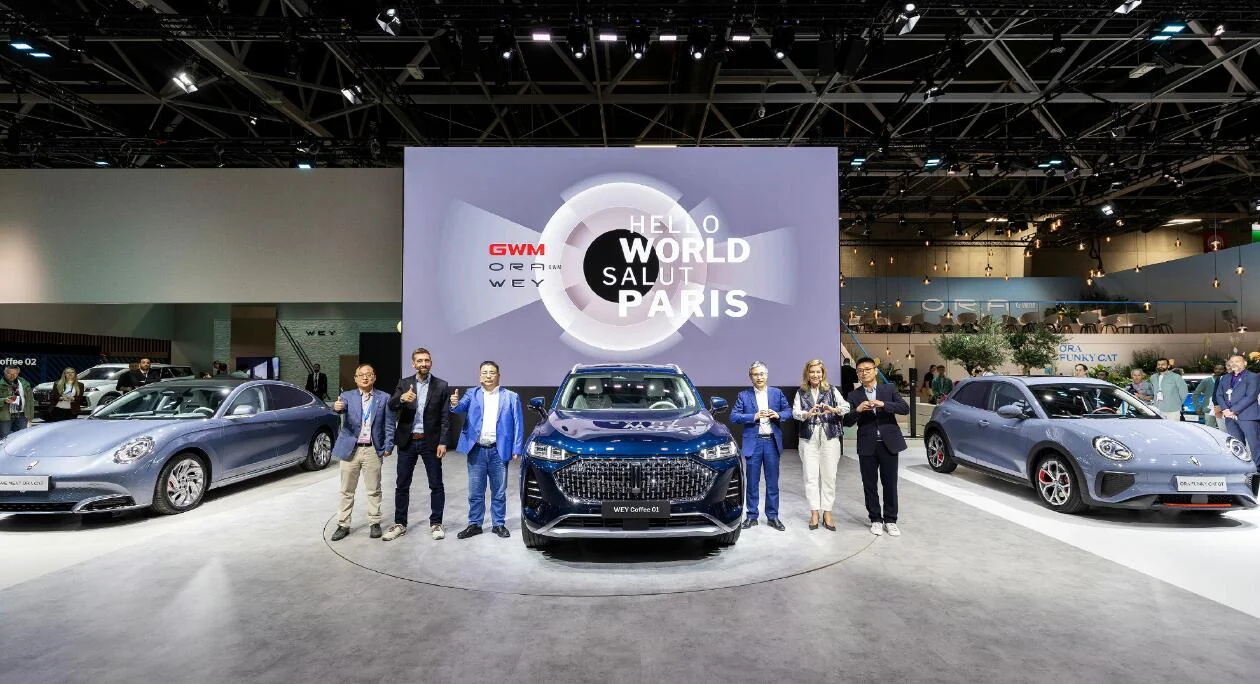
“As the dust settles on this year’s Beijing Motor Show, which put the Geneva Motor Show in February to shame with its packed halls, Sophus3 will soon be embarking on its third annual analysis of Chinese manufacturers in Europe. The Sophus3 eDataXchange partnership with more than 20 leading car brands has told the incredible story of growth in digital market share for the Chinese car industry, now touching 3% of all brands combined. If you add Volvo, that number more than doubles, something that would have seemed impossible a few years ago.”
Failures, newcomers and a price advantage
“Some Chinese brands, notably HiPhi, have already failed in Europe, but new ones will soon take their place. For example, Chinese smartphone maker Xiaomi, whose first car sold out in under 24 hours in China, just a few weeks after we heard that the all-conquering Western smartphone brand Apple had cancelled its long-running auto programme, ‘Project Titan’.
The price advantage enjoyed by Chinese EVs is significant, with a typical model 20% cheaper than its equivalent from European brands. And this is likely to drive even fiercer competition in the future. The average retail price of an EV in Europe was more than €65,000 in the first half of 2023, compared with just over €31,000 in China, according to research by Jato Dynamics.
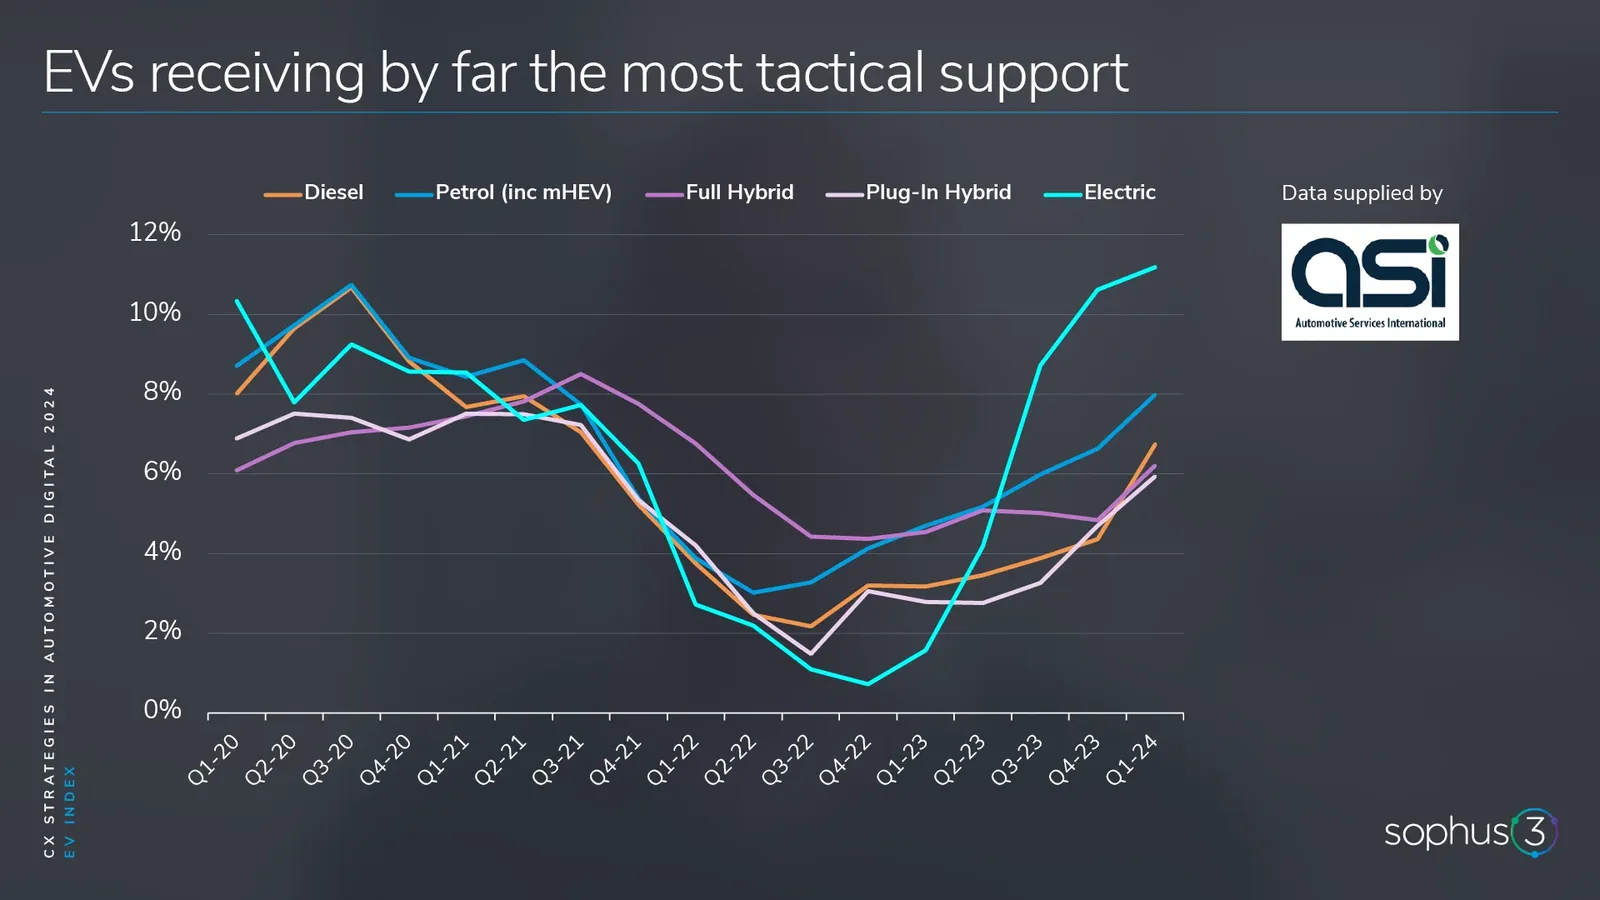
No wonder then that money is being thrown at incentives to encourage more EV sales by traditional brands, as illustrated by this piece of analysis by UK retail specialist ASI, which clearly shows how EVs have received the most support of any fuel type since the end of 2022.”
The online landscape for Chinese brands
“Anyone hoping that the European Commission will increase import tariffs when it concludes its investigation in the autumn is likely to be disappointed, such is the price advantage of Chinese brands. Soon, several of them may be manufacturing in Europe too, from BYD in Hungary to Chery in Barcelona, and Leapmotor in Poland.
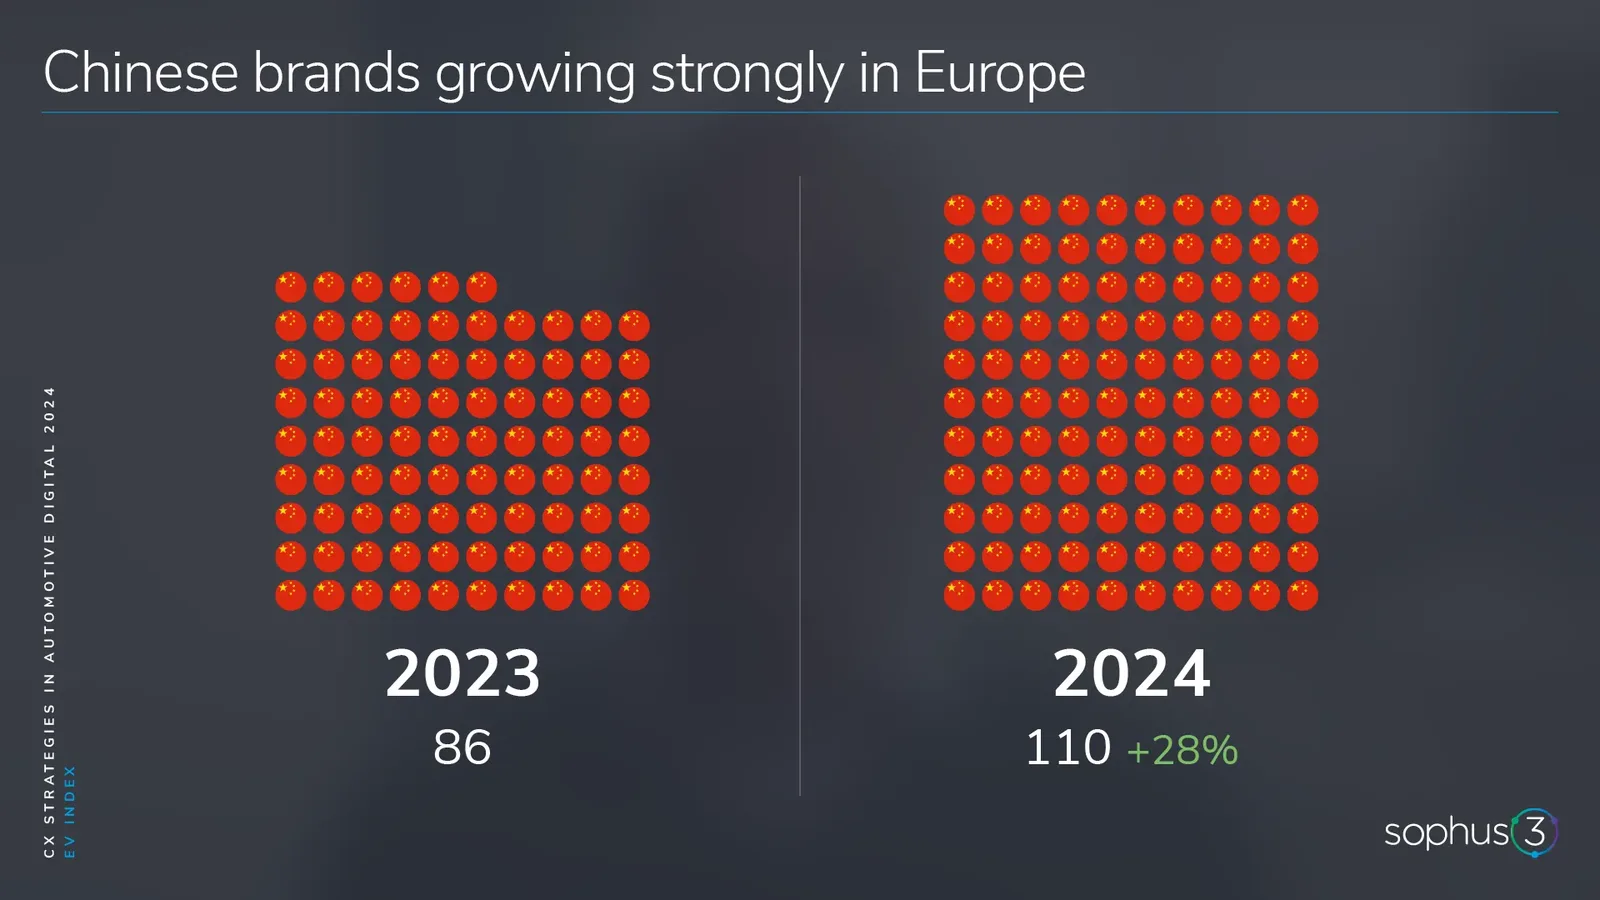
So what is the current online landscape for Chinese brands? Our research has identified 17 active brands across 13 European markets, led by Sweden, with no fewer than 11. Not all EU5 markets are seeing sustained growth in Chinese brand market share, with the UK seeing a 10% increase in our latest quarterly report, compared with a 2% decline for Germany.”
Questions or comments? Contact Sophus3.
Transcript of the Sophus3 video published on 2 July 2024. Figures relate to that period.